
Your EMI Is Fixed. Your Home Loan Isn’t.
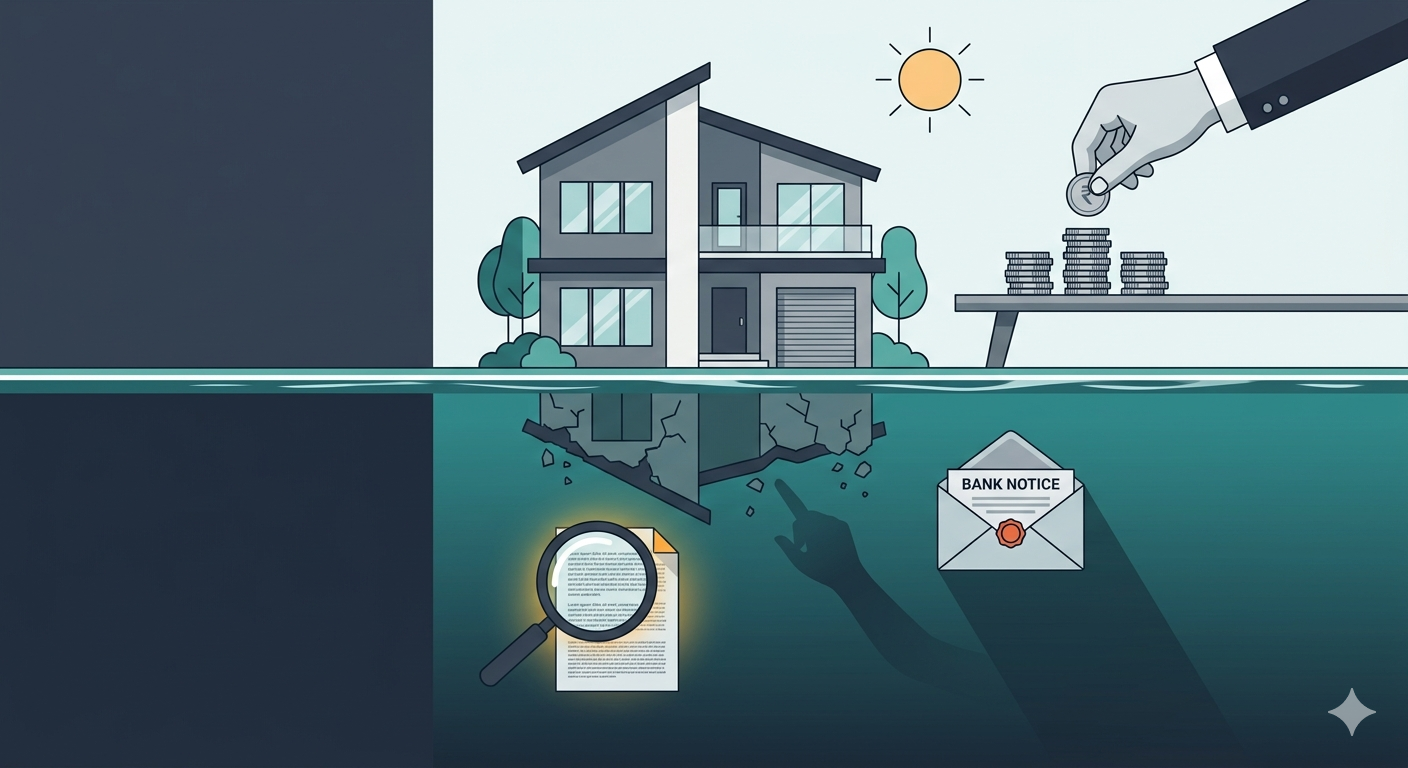
There’s a clause in almost every home loan agreement that can ask you for more money even when you’ve never missed an EMI.
Here’s how it works, and how to make sure it never catches you.
The Bottom Line: Right Upfront
Your EMI is the part of the deal you can see. The security sufficiency clause, is the part you signed without reading.
A home loan isn’t simply a debt you service every month. It’s a bet on the real estate market that you’ve quietly guaranteed with your own balance sheet. For most people, in most years, that bet pays off and the clause never stirs.
But “most years” isn’t a strategy. Read what you signed. Keep your loan shrinking faster than your worry. And hold enough in reserve that, if the market ever turns against you, the letter from your bank is an inconvenience, not a catastrophe.
What’s all this about?
You’ve never missed an EMI. Not once in three years. Every month, on the dot, the money leaves your account.
Then one day, a letter arrives from your bank. It doesn’t say you’ve defaulted. It says your property isn’t worth enough anymore, and you have 30 days to either pay down a chunk of your loan or pledge another asset as security.
You read it twice. You’ve done everything right. How is this even possible?
It’s possible because of a clause you almost certainly signed without reading.
I’ve read these agreements line by line with clients more times than I can count. In all those years, I can think of maybe two people who had noticed this clause on their own. Everyone else signed it the way we all sign things we assume are just standard.
The part of the deal you can see, and the part you can’t
Most of us think of a home loan as a fixed monthly expense. Predictable. Boring. The EMI is the EMI, and as long as you pay it, the bank has no business with you.
That’s the illusion.
Your loan agreement treats you as more than a borrower. It treats you as a guarantor of your property’s market value. Buried in the fine print of nearly every home loan is a security sufficiency clause, sometimes called a security impairment or additional security clause. In plain English, it says the loan must stay adequately covered by the property for the entire tenure. If the property’s value falls far enough below what you still owe, the bank can ask you to make up the difference: prepay part of the loan, or pledge additional collateral.
It isn’t even hidden. HDFC’s own loan guide says outright that if the property alone becomes insufficient security “due to fall in market prices or deterioration or destruction,” the lender may call upon you to provide more. Most lenders carry a version of the same language.
To see why it bites, you need one number: LTV, or loan-to-value. It’s simply your outstanding loan divided by your property’s current value. RBI caps it on the day you borrow: 90% for homes up to ₹30 lakh, 80% up to ₹75 lakh, and 75% above that. But here’s the catch nobody mentions. That cap only applies at sanction. After that, if your property’s value falls while your loan is still large, your real LTV can quietly climb past 100%, and that is exactly the trigger the clause is written for.
What it looks like in real life
The story below is a composite, not one real client, but I’ve watched versions of it play out more than once. Walk through the numbers with me, because that’s where it stops being abstract.
Picture a software professional who buys a ₹1 crore under-construction flat in a fast-growing suburb in 2022.
Because the loan is on a high-value home, RBI rules cap the financing at 75%. So the bank lends ₹75 lakh; the buyer puts down ₹25 lakh. A textbook, responsible purchase.
Then 2024 happens. The builder goes bankrupt. Construction stops. A civic mess engulfs the locality: water-logging, an environmental dispute, legal notices. Prices in the micro-market crash 35%. The flat is now worth ₹65 lakh.
Meanwhile, the loan has barely moved. Early EMIs are mostly interest, so after two years the outstanding is still around ₹72 lakh.
Do the math. ₹72 lakh owed against a ₹65 lakh property. The effective LTV is now about 111%. The bank is owed more than the home is worth.
During an annual revaluation, the bank’s risk team flags the security as “severely impaired” and invokes the clause. The demand: either prepay around ₹7 lakh within 30 days to bring the loan back in line with the property, or pledge an unencumbered asset (a fixed deposit, an insurance policy, a parent’s property) worth about ₹10 lakh to cover the gap.
The borrower hasn’t missed a single payment. It doesn’t matter. The risk that triggered the letter was never about their behaviour. It was about the market, and they had quietly guaranteed it.
“Surely banks don’t really do this”
Here’s the fair caveat: against a regular borrower who keeps paying, banks rarely pull this trigger. The reputational damage and the cost of litigation usually aren’t worth it. So if you’re well inside your limits, you can sleep at night.
So will your bank really do this to you? Probably not. But “probably not” is doing an enormous amount of work in that sentence, and I’ve learned the hard way not to bet a family’s home on it.
But rarely is not never, and Indian real estate has handed lenders the conditions to test it more than once.
The stalled-tower crisis (2017–2019). When Amrapali, Jaypee and Unitech projects froze across the NCR, tens of thousands of buyers were trapped, many of them on subvention loans, liable for EMIs on flats they could never occupy, while the half-built towers became near-worthless concrete. Over 1,500 buyers stopped paying, and were warned they would be treated as defaulters. What ultimately saved them wasn’t their loan agreement: it was the Supreme Court, which in an extraordinary intervention ordered banks not to tag these accounts as NPAs, not to levy penalties, and not to wreck their credit scores. Read that again. It took the highest court in the country to protect them. That is not a financial plan. That is a rescue.
The 2008 crash. After Lehman collapsed, prices in Mumbai and Delhi fell roughly 25% in two years, and the luxury and speculative pockets fell hardest. Leveraged investors who had bought multiple high-value flats suddenly found their LTVs breached. Lenders responded by holding back undisbursed loan tranches and demanding fresh margin before releasing more. The clause did its job, quietly.
Chennai 2015, Kerala 2018. Floods don’t wait for a market cycle. They destroy the collateral physically and instantly. After the Kerala floods, the rating agency India Ratings noted plainly that damaged property pushes up the LTV and sets up a “strong haircut” for lenders. In practice, lenders mostly chose relief over recovery: RBI’s natural-calamity rules allowed moratoriums, and several housing financiers deferred rate hikes and waived penalties. But notice the pattern again. The cushion came from the regulator and the lenders’ goodwill, not from the contract. An uninsured family whose home was destroyed still owed the full loan on a worthless asset.
The through-line across all three is the uncomfortable one. When borrowers were spared, it was because a court, the RBI, or a government stepped in. The loan agreement itself was never on their side.
If there’s one lesson I take from all of this, it’s simple — don’t build your plan around being rescued. Rescue is what happens when the system fails slowly enough for someone to step in. You want to be the person who never needed one.
So what should you do about it?
You can’t control the property market. You can control your exposure to this clause. Five things:
1. Read the clause before you sign. Find the security-sufficiency or additional-security clause in your agreement, and ask your lender, in writing, what specifically triggers it and how much notice you would get. A clause you understand is far less dangerous than one you discover in a letter.
2. Be most careful with under-construction and speculative property. That’s the toxic combination: illiquid, price-volatile, and carrying possession risk. It’s exactly where values crater and clauses get tested.
3. Make your LTV fall, not rise. Prepay principal whenever you can, especially in the early years. The faster your outstanding drops below your home’s value, the smaller the gap that could ever be “called,” and the more cushion you have if prices wobble. This is the lever I push hardest with clients, because it quietly removes the whole problem before it can ever start.
4. Keep your property properly insured. Most home loans require it; many borrowers let it lapse. Adequate cover means a fire, a flood or structural damage doesn’t instantly wipe out the asset backing your loan.
5. Keep a buffer that could absorb a demand. Your emergency fund isn’t only for job loss and medical bills. A healthy reserve, or unpledged liquid assets, is also what turns a sudden collateral call from a crisis into a phone call.
And keep your paperwork: valuation reports, insurance, payment history. If a revaluation ever feels unfair, documentation is how you push back.
Sources & further reading
- HDFC Home Loans, Important Clauses in Your Home Loan Agreement (spells out the security-sufficiency / additional-security clause)
- Axis Bank, Loan to Value (LTV) Ratio (RBI’s 90% / 80% / 75% LTV slabs by loan size)
- Business Standard, How SC stood by Amrapali homebuyers (no NPA tagging, no penalties for stuck subvention-scheme buyers)
- Business Today, How the real estate sector is adjusting to survive (~25% housing-price fall in Mumbai and Delhi after 2008)
- Moneylife, Lenders with Exposure to Kerala Bracing for a Jolt Amid Floods: Ind-Ra (flood damage raising effective LTV and the resulting lender “haircut”)
- Business Standard, IBHFL postpones rate hike for Kerala customers by 2 months (example of lender relief under RBI’s natural-calamity framework)
This article is for general education, not legal or financial advice. Home loan agreements differ from lender to lender, so read your own, and confirm the exact wording and your options with your lender or a qualified professional before acting.
Leave a Reply